A Forensic Scoring Framework for Exit Risk Across Corridors, Price Bands, and Asset Classes (October 2026)
Between 2019 and the second quarter of 2026, benchmark capital values across the National Capital Region surged significantly: ANAROCK recorded residential property price jumps of 125% in Noida and 117% in Gurugram. Over the same seven-year window, however, gross residential rental yields expanded by only 70 to 80 basis points.
While prices moved up rapidly, physical transaction velocity did not maintain the same pace. In the first half of 2026, Tier-1 primary market sales volume stood near Rs 3.63 lakh crore (almost flat compared to the previous year), while the absolute number of homes sold dropped by 2% to 2.58 lakh units. Simultaneously, new project launches grew by 7%.
The price is the headline. The buyer is the constraint.
Key Market Realities at a Glance
- Capital Value Growth: NCR average residential capital values reached Rs 8,333 per sq ft in Q2 2026, marking a 9.4% year-on-year increase.
- Inventory Overhang Split: Knight Frank data shows NCR quarters-to-sell standing at 7.9 in H1 2026. Gurugram recorded an overhang of 9.6 quarters against 59,727 unsold units, while Ghaziabad turned inventory in 3.2 quarters.
- Ticket Size Shift: Homes priced above Rs 1 crore captured 54% of sales value in major markets, while sub-Rs 50 lakh housing transactions dropped sharply.
- Mandatory Friction: Stamp duty, registration, and brokerage absorb roughly 7% to 10% of gross capital value before an investor realizes any net gain.
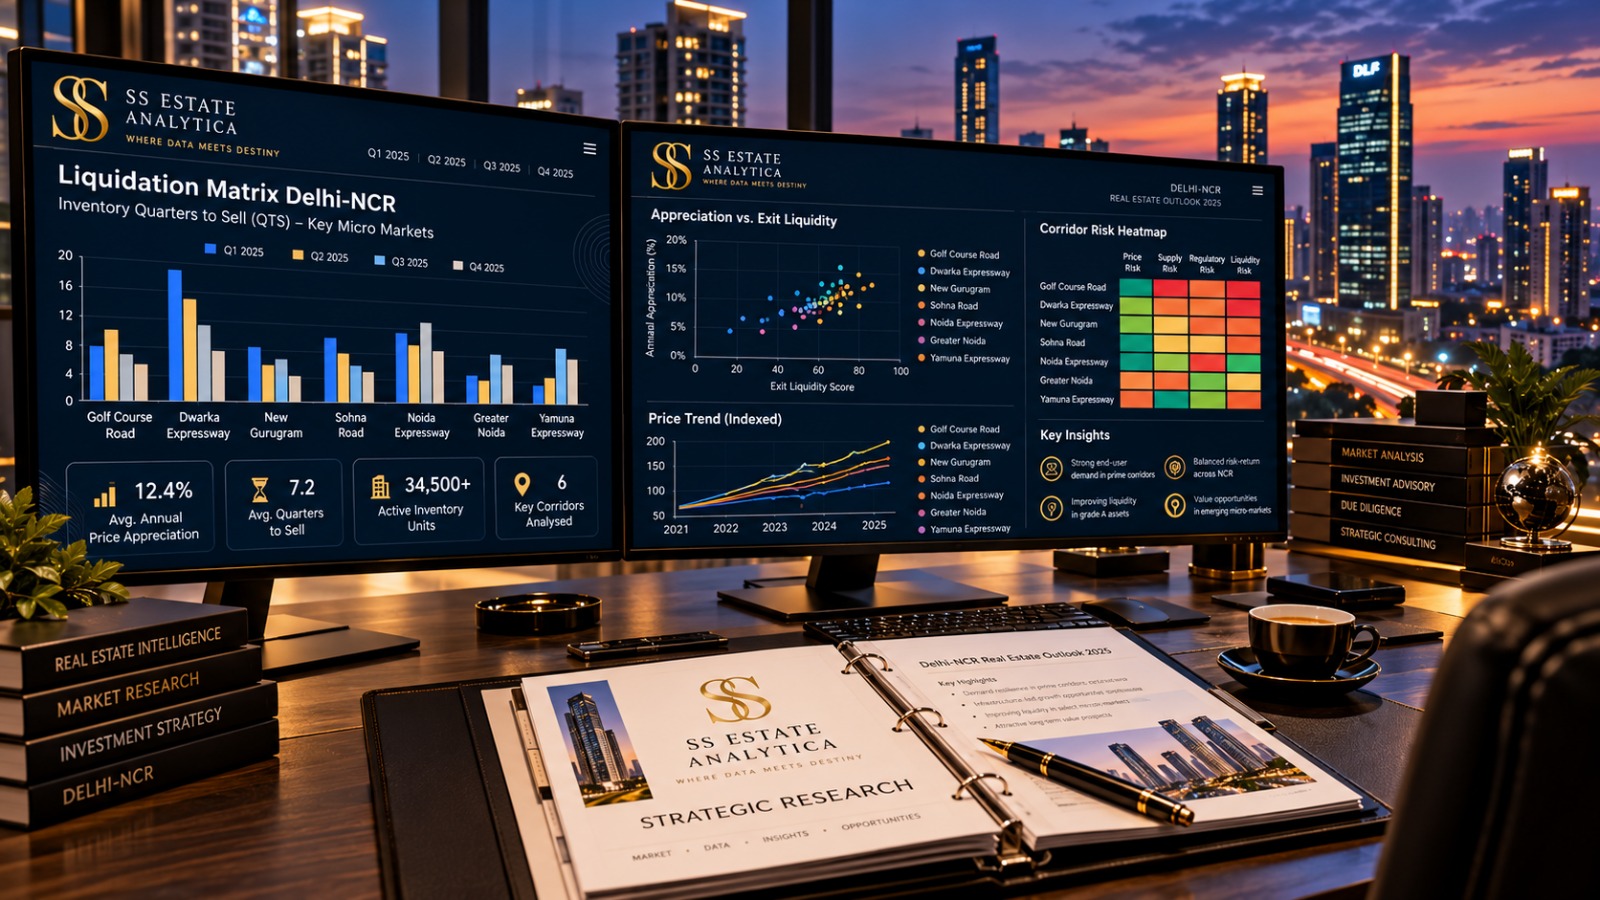
1. Understanding the Liquidation Matrix: APS vs. ELS
Quoted appreciation represents an upper bound, not an immediate cash forecast. When an owner needs to liquidate an asset inside a 90-day window, they are not trading an index—they are selling a single, specific property to a financed buyer after deducting taxes, duties, and discounts.
The Liquidation Matrix evaluates micro-markets across two core metrics:
- Appreciation Score (APS) [0 to 100]: Weights historical multi-year price growth (40%), upcoming infrastructure catalysts (25%), micro-market supply scarcity (20%), and rental yield trajectory (15%).
- Exit Liquidity Score (ELS) [0 to 100]: Weights quarterly absorption rates (30%), end-user presence over investors (20%), ticket size eligibility (15%), ready versus under-construction status (15%), title and legal clarity (10%), and secondary market resale depth (10%).
- The Liquidation Gap (APS – ELS): A large positive gap signals paper wealth, where asset pricing has outpaced secondary exit depth.
Matrix Quadrants
- Compounders (High APS, High ELS): Both capital appreciation and exit liquidity function efficiently. These are typically ready, occupied, end-user residential assets.
- Paper Gains (High APS, Low ELS): Strong quoted prices on paper, but turning the asset into cash requires prolonged waiting or a steep price haircut.
- Cash Parks (Moderate APS, High ELS): Highly liquid exits with moderate long-term price upside, suitable for shorter capital horizons.
- Traps (Low APS, Low ELS): Stagnant pricing coupled with weak secondary buyer demand.
2. Five Reasons Why Quoted Prices Do Not Equal Instant Cash
- The Quoted Price is an Ask: Portal listings and neighbor asking rates are not standing buy orders. Secondary transactions remain strictly bilateral, where buyers aggressively price in construction age, layout inefficiencies, and pending dues.
- Buyers Rely on Financing: Genuine end-users require bank appraisals, legal checks, and home loan sanctions. Unconditional cash buyers who can close in weeks are rare and demand double-digit discounts.
- Higher Ticket Sizes Thin the Pool: The average Tier-1 ticket size touched Rs 1.41 crore in H1 2026. With Gurugram developers bringing extensive luxury pipelines, buyers have substantial primary choice, lengthening resale cycles for existing owners.
- Entry and Exit Friction: Round-trip transaction expenses (stamp duty, registration, and dual brokerage) sit between 7% and 10%. Short holding periods struggle to overcome this initial hurdle.
- Uneven Supply Overhang: Unsold inventory across eight major metros reached 5.26 lakh units in mid-2026. Across the NCR, inventory absorption varies sharply—from 3.2 quarters in Ghaziabad to nearly 10 quarters in Gurugram.
3. The 90-Day Exit Haircut: From Rs 3.85 Cr Paper Value to Rs 3.21 Cr Cash
To understand the difference between paper appreciation and realized cash, consider a ready residential apartment in Gurugram purchased at Rs 2.50 crore:
- Initial Purchase Price: Rs 2.50 Crore
- Entry Friction (7% Stamp & Registry): +Rs 0.175 Crore (Total capital deployed: Rs 2.675 Crore)
- Quoted Market Value at Year 5: Rs 3.85 Crore (Reflecting a 9.0% headline CAGR on purchase price)
- Brokerage & Legal Costs (-2%): -Rs 0.08 Crore
- Forced 90-Day Liquidity Discount (-8%): -Rs 0.30 Crore
- Actual Realized Cash in Hand: Rs 3.21 Crore
While the brochure and portal index reflect a 9% annualized gain on the original agreement value, the actual cash return on deployed capital drops to approximately 3.7% CAGR under a forced 90-day liquidation timeline.
When the same asset is liquidated without time distress over two quarters with minimal negotiation, it realizes closer to Rs 3.60 crore (~6% net return). Liquidity is fundamentally a function of time.
4. Delhi-NCR Overhang by Price Segment
Liquidity in Delhi-NCR is governed more by ticket size than pin code:
- Rs 50 Lakh to Rs 1 Crore: 14.4 Quarters to Sell. This segment faces the highest inventory drag as middle-income buyers deal with higher borrowing costs and inflation.
- Rs 1 Crore to Rs 2 Crore: 7.1 Quarters to Sell. Reflects stable end-user turnover for family apartments.
- Rs 2 Crore to Rs 5 Crore: 4.2 Quarters to Sell. The fastest-clearing residential segment across NCR, supported by corporate professionals and lifestyle upgraders.
- Overall Market Benchmark: NCR overall averages 7.9 quarters, Gurugram sits at 9.6 quarters, and Ghaziabad clears in 3.2 quarters.
5. Seven Strategic Portfolio Rules
- Price the Exit Before Entering: If an 8% liquidity discount damages your financial safety net, the asset ticket is too large for your balance sheet.
- Differentiate Primary Bookings from Resale Liquidity: Strong developer launch bookings do not guarantee that individual secondary units can be sold quickly. Look for verified registry transfers and secondary bank disbursements.
- Choose Ready Assets When Gaps Widen: Under-construction properties offer flexible payment plans but carry severe exit illiquidity if an investor needs capital prior to completion.
- Track the Price Band Closely: Cheaper properties do not automatically mean faster sales. A Rs 75-lakh home takes significantly longer to clear in the current market than a ready Rs 3-crore unit.
- Deduct Friction on Both Sides: Account for entry stamp duties and exit brokerage in baseline underwriting models.
- Consider Refinancing Over Forced Selling: If a property has a clear title and banking support, obtaining a Loan Against Property (LAP) is frequently more cost-effective than taking a large secondary market discount.
- Monitor Handover Milestones: Large-scale project deliveries and completed stalled projects introduce fresh secondary supply, directly altering local exit liquidity scores.
Advisory Desk Contact & Research Access
For specific corridor scorecards, verified secondary price comparables, and asset exit diligence across Delhi-NCR:
Statutory Disclaimer: This report is compiled by SS Estate Analytica solely for educational, analytical, and informational purposes as of October 2026. It does not constitute formal valuation under any statutory standards board, nor an offer or solicitation to buy or sell real estate assets. Past price changes do not guarantee future returns or liquidity. Independent legal, technical, and financial verification is advised before executing property transactions.