Executive Research Note
Date: 18 October 2026 | Classification: Advisory Research
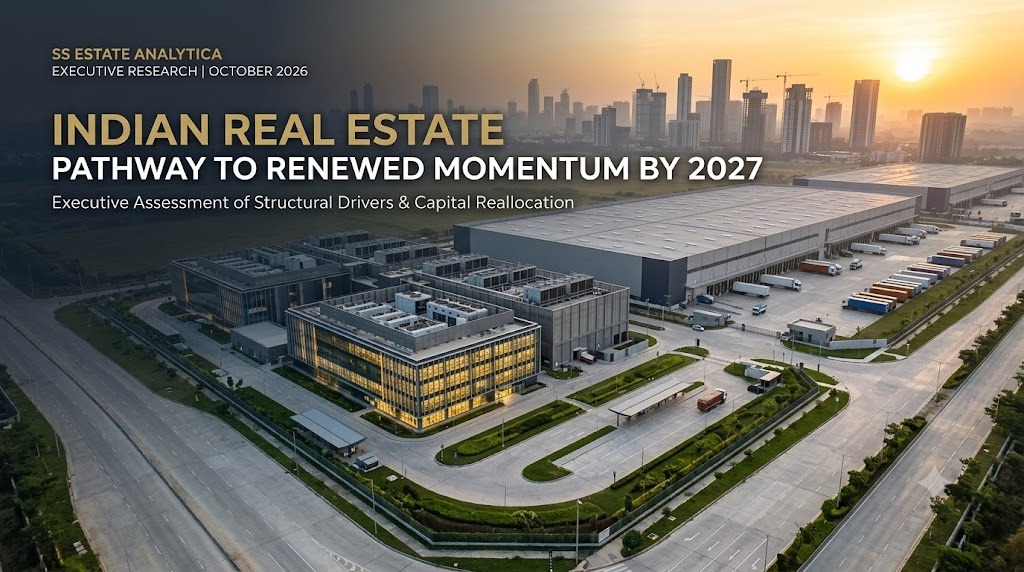
Indian Real Estate: Pathway to Renewed Momentum by 2027
Executive assessment of structural drivers, capital reallocation, and emerging sectoral opportunities across Indian real estate.
4% – 6%
Sales Value Growth (FY27)
Crisil projection; volumes flattish at 0-2%
38% – 40%
Premium Launch Share
Projected for FY27 (up from ~12% in FY22)
72.5M sq ft
Warehousing Absorption
Record annual absorption logged in 2025
~2 GW
Data Centre Capacity
On-track operational capacity by end-2026
1. Executive Summary
Indian real estate is navigating a transition from a multi-year post-pandemic upcycle into a period of moderated residential growth. Crisil Ratings and peer agencies project housing sales-value growth of 4–6% in FY27, with volume demand remaining broadly flattish (0–2%) on elevated prices and a high base from FY22–FY25. Price growth is expected to moderate to 3–5%, while the premium and luxury segments continue to dominate launches and absorption.
Despite near-term residential softness, five converging factors support the prospect of renewed momentum by 2027:
- Equity-market volatility driving domestic capital toward real assets.
- SEBI-influenced constraints on mutual-fund bullion and silver channels.
- Potential NRI re-entry linked to tightening US H-1B visa policies.
- Rapid expansion of data-centre infrastructure and its massive ancillary real estate demand.
- Sustained strength in Grade-A warehousing and logistics driven by manufacturing and supply-chain formalisation.
Strategic Takeaway
Long-term forecasts (Colliers-CII, CREDAI-Colliers, FICCI-KPMG) place the market at USD 5–10 trillion by 2047, contributing 15–20% of GDP. The 2027 window represents a strategic inflection for capital reallocation and specialised infrastructure rather than a generic residential volume surge.
2. Market Context (Late 2026)
Residential sales volumes in the top seven to eight cities declined approximately 14% year-on-year in 2025 (Anarock), while overall sales value was insulated by premiumisation. Homes priced above Rs 1 crore now form the clear majority of sales in leading markets. Premium and luxury inventory is projected to capture 38–40% of all launches in FY27 (compared to ~12% in FY22).
In contrast to residential volume moderation, commercial and specialised segments display sustained operational strength:
| Sector | Operational Status (2025–2026) | Growth Catalyst |
|---|---|---|
| Commercial Office | Leasing resilience across Tier-1 hubs | Global Capability Centres (GCCs) expansion |
| Warehousing / 3PL | Record 72.5M sq ft absorbed in 2025 | Manufacturing PLI schemes and e-commerce recovery |
| Data Centres | Tracking ~2 GW operational by end-2026 | AI enterprise workloads & USD 38B H1 2026 commitments |
3. Principal Drivers: The 2027 Convergence
3.1 Equity-Market Volatility and Capital Rotation
Indian equity markets have faced extended corrections and heightened volatility in 2026 driven by elevated global bond yields, geopolitical unrest, energy volatility, and persistent foreign-portfolio (FPI) outflows. The Nifty Realty index participated in this broader sell-off despite resilient underlying operational metrics in commercial and industrial sub-sectors.
Historically, prolonged equity market corrections trigger a defensive capital rotation into income-generating, collateralised physical assets. High-net-worth individuals and domestic family offices are turning toward institutional real estate and listed REITs to secure inflation protection and stable yields into 2027.
3.2 Mutual-Fund Constraints on Bullion and Silver
In October 2026, multiple domestic fund houses suspended fresh lump-sum allocations, new SIP registrations, and switch-ins into Gold and Silver ETF Fund-of-Funds (FoFs), guided by informal regulatory interventions to curb import-driven pressure on the Indian rupee.
With entry channels into precious metal paper instruments constrained—and physical retail bullion carrying steep customs and retail markups—a measurable share of affluent domestic savings is pivoting toward physical real estate as an alternative long-horizon store of value.
3.3 NRI Re-entry Linked to US H-1B Policy Tightening
US policy headwinds—including proposed petition fee spikes up to USD 100,000 for specific classifications and temporary suspensions of PERM processing across major enterprise IT employers—have introduced career uncertainty for technology professionals on H-1B visas.
Channel checks by ANAROCK and Colliers indicate that returning tech executives are directing capital into ready and near-ready homes in major tech hubs (Bengaluru, Hyderabad, Pune, Chennai, and select Tier-2 corridors). Typical residential purchasing budgets fall between Rs 1.5 Crore and Rs 5 Crore, providing durable support to premium absorption.
3.4 Data-Centre Infrastructure and Ancillary Ecosystem Demand
India’s operational data centre capacity is tracking toward 2 GW by end-2026, with an active pipeline aiming for 3.8–5+ GW by 2030. In H1 2026 alone, investment commitments touched USD 38 billion, bringing cumulative commitments since 2021 to roughly USD 173 billion across Mumbai, Chennai, Hyderabad, Delhi-NCR, Pune, and emerging nodes like GIFT City and Noida.
The Square Yards Ecosystem Multiplier
A proposed 9 GW nationwide data-centre pipeline is projected to create ~4.33 lakh ecosystem technology jobs. This employment base will drive approximately 195 million sq ft of residential housing demand by 2030, concentrated within a 5–15 km catchment radius of major server parks.
3.5 Warehousing and Logistics Expansion
Total warehousing stock in India has crossed 550–610 million sq ft, with Grade-A share continuing to rise and projections touching 850 million sq ft by 2030. Driven by Production-Linked Incentive (PLI) manufacturing schemes, supply chain decentralisation, and automotive clusters, prime logistics vacancy remains tightly contained.
Institutional capital strongly favours Grade-A warehousing due to 10–15 year leases, credit-rated tenant profiles, and direct alignment with national infrastructure initiatives aimed at lowering overall logistics costs as a percentage of GDP.
4. Synthesis and Outlook to 2027
The five core drivers do not operate in isolation; they are mutually reinforcing across institutional and domestic capital layers:
Capital Reallocation
Equity volatility and constrained bullion paper redirect domestic household surpluses toward real assets.
Targeted NRI Inflows
Tech professionals facing visa headwinds backstop premium residential and commercial GCC uptake.
Infrastructure Absorption
Data centre parks and multi-modal logistics hubs absorb institutional capital and drive ancillary housing.
Balance Sheet Discipline
Developers prioritize controlled launches in high-margin premium segments over speculative volume spikes.
By late 2026 into 2027, stabilising interest rate cycles and the easing of municipal approval bottlenecks are expected to visibly improve absorption metrics. Momentum will surface first in industrial logistics, server infrastructure corridors, and premium tech-adjacent residential assets.
5. Principal Risks & Monitoring Framework
- Global Macro Headwinds: Sharp upward revisions in US/Indian bond yields compressing institutional allocations.
- Input Cost Pressures: Sustained construction material inflation or regional labour shortages delaying project delivery cycles.
- Infrastructure Utilities Lag: Power grid, sub-station, and water allocation deficits impacting data centres and large industrial projects.
- NRI Compensation Realignment: Muted domestic tech compensation packages reducing the conversion of NRI inquiry volumes into registered sales.
- Micro-Market Overhang: Uncalibrated luxury launch waves in specific emerging corridors causing localized absorption drag.
Institutional Advisory & Due Diligence
Engage the SS Estate Analytica Research Desk
Access bespoke institutional underwriting models, corridor-level exit scores, and technical due diligence reports across Delhi-NCR and key Indian micro-markets.
Head Office: WorldMark, Aerocity, New Delhi • Servicing: Lucknow, Mumbai, Bengaluru
