Investor Intelligence Brief
October 2026 | UPEIDA Corridor Assessment
UPEIDA Industrial Plot Scheme 2026: Eight Integrated Manufacturing & Logistics Clusters
Independent market assessment, comparative corridor ratings, land premium structures, and gestational allocation options for manufacturing and logistics investors.
8 Clusters
Phase 1 Allotment
Part of planned 27 IMLCs across 26 UP districts
₹3,800 – ₹11,470
Land Premium / sq m
Hardoi lowest at ₹3,800; Meerut anchor at ₹11,470
2.5% + GST
Annual Lease Rent
Calculated on plot premium; ₹59,000 processing fee
3 Expressways
Strategic Arteries
Ganga, Bundelkhand & Agra-Lucknow corridors
1. Scheme Overview & Corridor Alignment
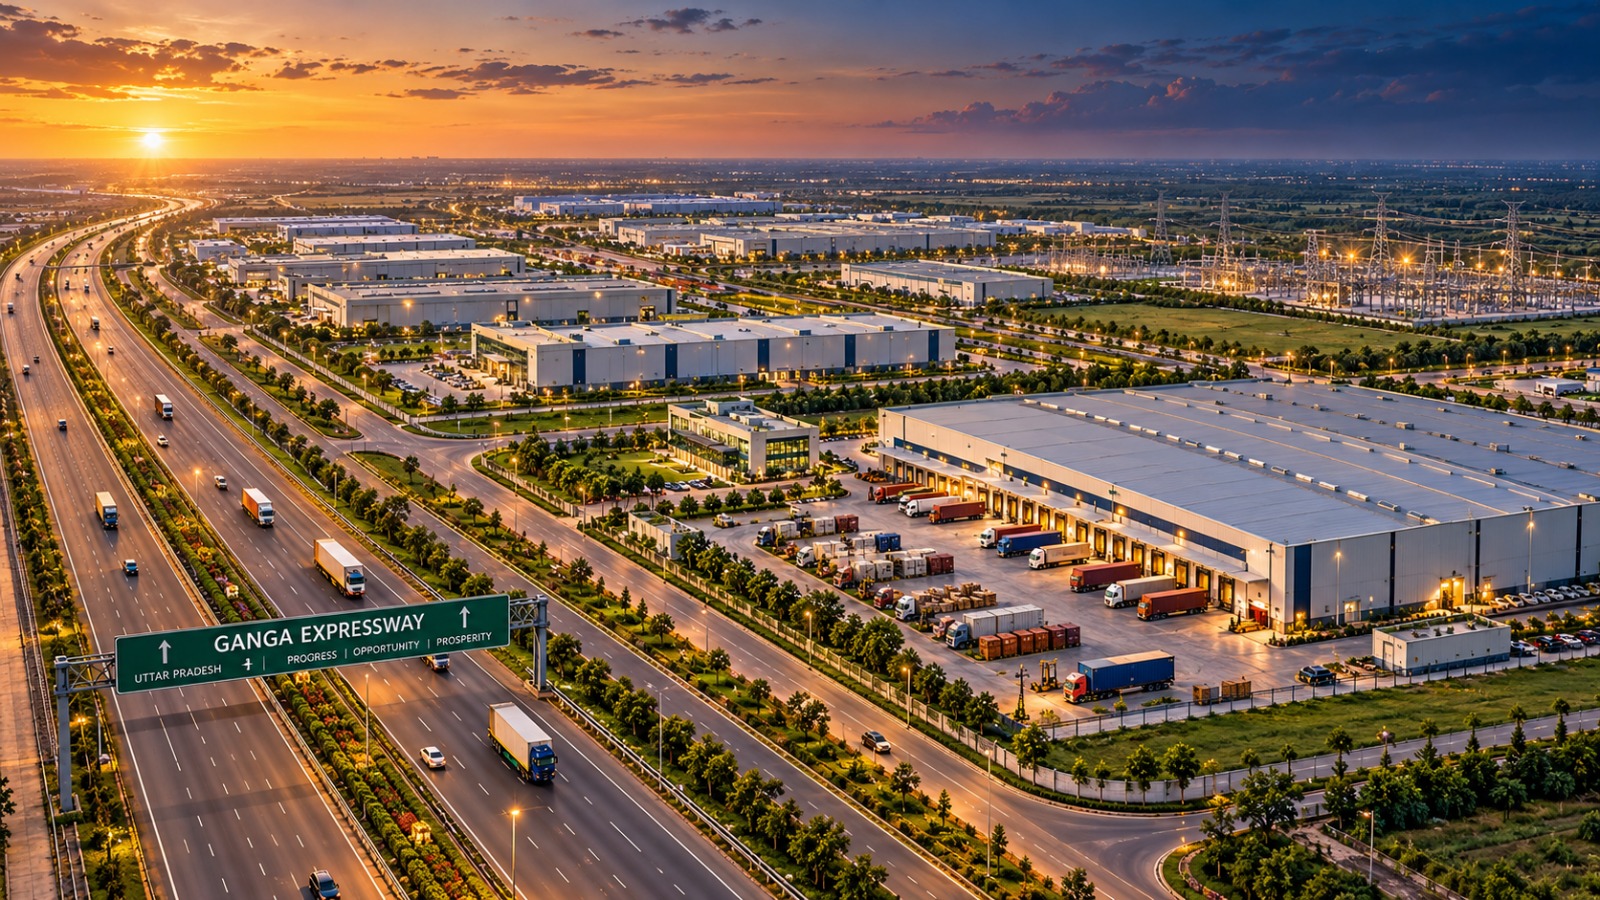
On 16 October 2026, the Uttar Pradesh Expressways Industrial Development Authority (UPEIDA) formally launched its industrial plot allotment scheme across eight Integrated Manufacturing and Logistics Clusters (IMLCs). The initiative forms part of the state’s broader blueprint to build 27 manufacturing nodes across 26 districts, transforming high-speed expressway corridors into self-sustaining freight and production hubs.
Offered under long-term industrial lease agreements, the plots target manufacturing entities, third-party logistics (3PL) operators, and ancillary packaging and cold-chain suppliers. Applications are processed digitally via Uttar Pradesh’s single-window portal, Nivesh Mitra.
2. The Eight Clusters: Premium & Connectivity Matrix
| Cluster | Premium (₹/sq m) | Planned Area | Expressway Corridor | Investment Theme |
|---|---|---|---|---|
| Meerut | ₹11,470 | 529 acres | Ganga Expressway | NCR-adjacent, high-demand logistics |
| Auraiya | ₹7,920 | 324 acres | Bundelkhand Expressway | Emerging corridor, mid-premium value |
| Sambhal | ₹5,000 | 591 acres | Ganga Expressway | Large-scale cluster, logistics anchor |
| Etawah | ₹4,550 | 217 acres | Agra-Lucknow Expressway | Central UP freight connectivity |
| Firozabad | ₹4,400 | 344 acres | Agra-Lucknow Expressway | Established manufacturing & glass cluster |
| Shahjahanpur | ₹4,400 | 252 acres | Ganga Expressway | Northern agricultural/industrial expansion |
| Hamirpur | ₹3,900 | 259 acres | Bundelkhand Expressway | Value entry with long-term infrastructure upside |
| Hardoi | ₹3,800 | 335 acres | Ganga Expressway | Lowest entry premium; maximum relative upside |
*Planned areas based on UPEIDA notifications. Premiums exclude processing fee (₹59,000), 2.5% annual lease rent, and GST.
3. Independent Return Framework & Corridor Ratings
Applying SS Estate Analytica’s corridor underwriting models, we benchmarked each cluster based on entry valuations, regional connectivity, and anticipated demand from manufacturing and 3PL occupiers:
| Cluster | Premium Tier | Indicative CAGR | Primary Driver | SS EA Rating |
|---|---|---|---|---|
| Meerut | Highest | 8% – 12% | NCR proximity + Ganga Expressway | A |
| Hardoi | Lowest | 12% – 18% | Value entry + Ganga corridor upside | A- |
| Sambhal | Mid | 10% – 15% | Large scale + freight connectivity | A- |
| Auraiya | Mid-High | 9% – 14% | Bundelkhand industrial emergence | B+ |
| Hamirpur | Low | 11% – 16% | Value entry + regional development | B+ |
| Shahjahanpur | Mid-Low | 10% – 14% | Ganga northern expansion | B+ |
| Firozabad | Mid-Low | 9% – 13% | Agra-Lucknow + glass manufacturing | B |
| Etawah | Mid-Low | 9% – 13% | Central state transit node | B |
4. Gestational Options & Implementation Strategy
Short-Term (1–3 Years)
Focuses on allotment acquisition, site possession, and initial trunk infrastructure delivery. Capitalizes on early entry-stage appreciation as cluster visibility increases.
Medium-Term (3–7 Years)
Trunk utilities stabilize and operational manufacturing or 3PL facilities take possession. Opens build-to-suit leasing opportunities (indicative yields: 6%–9% on built assets).
Long-Term (7+ Years)
Full ecosystem maturation across freight routes. Provides stabilized long-term rental income alongside substantial cumulative capital value growth for balance sheets.
Confidential Due Diligence
Request Full UPEIDA Cluster Dossier & Diligence
Fill out the form below. Our industrial research desk will forward cluster-level rate comparisons, Nivesh Mitra application checklists, and policy incentive models directly to your email.
Your information remains confidential and will be reviewed solely by the SS Estate Analytica Advisory Desk.
Prefer Immediate Consultation?
Connect directly with founder Manish Kr. Mishra and the research desk.
